 Main menu


Financial
Deutsche Bank: Regional Casino Stocks Present ‘Attractive Risk-Reward’ Profile
Posted on: October 6, 2026, 02:25h.
Last updated on: October 7, 2026, 07:22h.


Key Points
- Deutsche Bank upgraded regional casino operators Boyd Gaming and Penn Entertainment to "buy" from "hold," citing an attractive risk-reward profile following recent share sell-offs
- Analyst Steven Pizzella raised price targets to $99 for Boyd and $25 for Penn, noting that recent price declines were driven by macroeconomic sentiment rather than deteriorating operational fundamentals
- The report highlighted sequential growth momentum into October, ongoing capital investment projects, and disciplined deleveraging as key catalysts for both gaming equities through 2027


Regional casino stocks, including Boyd Gaming (NYSE: BYD) and Penn Entertainment (NASDAQ: PENN), have faced persistent selling pressure in recent months despite stable underlying operational fundamentals. That valuation disconnect is creating compelling opportunities across select regional operators, according to sell-side analysts at Deutsche Bank.
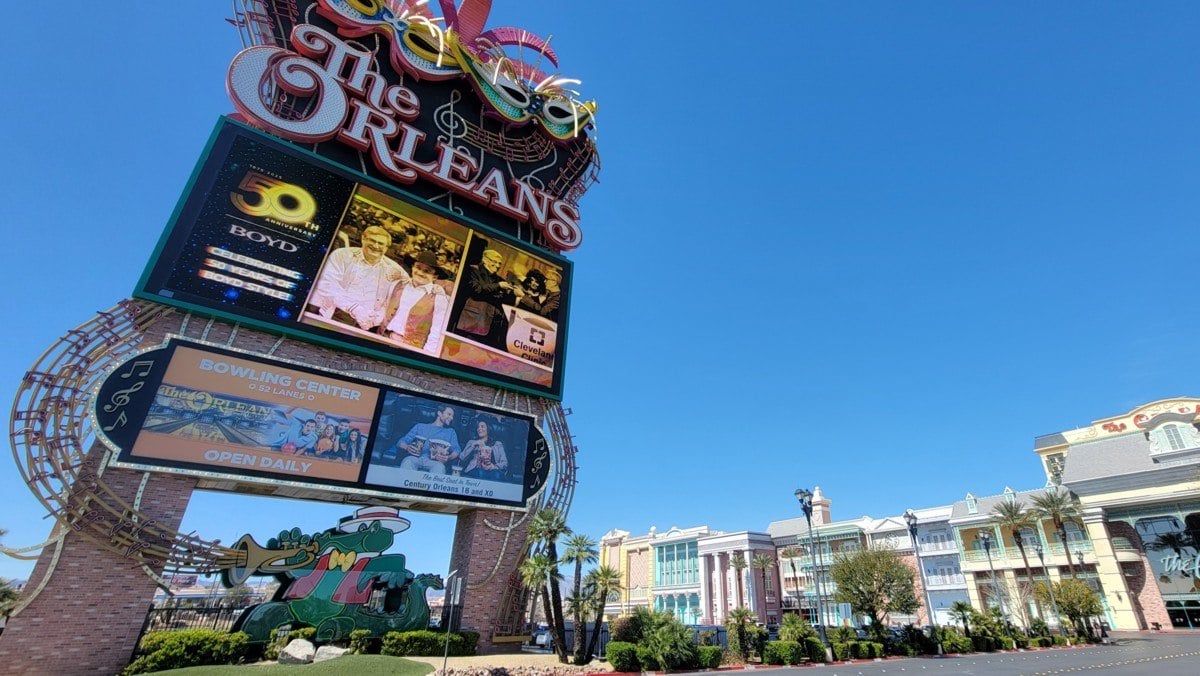
In a new report to clients, Deutsche Bank analyst Steven Pizzella upgraded Boyd Gaming (NYSE: BYD) and Penn Entertainment (NASDAQ: PENN), shares of which are off 21.6% and 31.4%, respectively, over the past 90 days, to “buy” from “hold.”
“We believe the recent selloff has been driven more by macro concerns and risk off sentiment than by any meaningful deterioration in company specific fundamentals,” observes the analyst. “As a result, we believe the group now offers a more attractive risk/reward profile.”
Pizzella raised his price target on Boyd Gaming to $99 from $98 while boosting his forecast on Penn to $25 from $23. The revised targets imply notable upside for the regional casino equities, which trade around $70 and $15.80, respectively.
Boyd Gaming: Clean Setup into 2027
In addition to macroeconomic pressures, including elevated inflation, high gas prices and a slack job market, regional casino stocks were confounded by one-off calendar woes, including one fewer Friday in August. However, Pizzella notes venues operated by Boyd and Penn showed signs of life in September and that momentum is carrying over into this month.
Regarding Boyd, the analyst says the Orleans operator’s setup is getting cleaner in the current quarter and into 2027 — bullishness that’s supported by the Suncoast Las Vegas renovation and a strong pipeline of growth projects that could stoke solid return on investment (ROI). Those efforts include “Par-A-Dice, Amelia Belle, Cadence Crossing, Suncoast, and The Orleans, alongside the late 2027 opening of Norfolk.”
Pizzella also praised Boyd’s management for a strong track record of capital allocation and the company’s efforts to return capital to investors.
“BYD’s capital return story remains attractive, in our view, supported by 2.6x net leverage on our year end 2026E, a ~$150 million quarterly share repurchase program (~12% annualized buyback yield), and a modest ~1.1% dividend yield,” says the analyst.
Penn Entertainment: Deleveraging & Growth Catalysts
Penn was a regional casino stock darling through the first half of this year, but rapidly lost that status as Treasury yields spiked, confirming the shares are tethered to interest rates. However, that implies that as the Ameristar deleverages, the shares could benefit.
“Continued progress toward sub 5.0x net leverage should broaden the potential investor base while increasing flexibility for incremental share repurchases,” observes Pizzella. “We estimate PENN would fall below 5.0x lease adjusted net leverage by year end 2027, even after incorporating ~$50 million of share repurchases into our forecasts.”
The analyst added that recently completed expansion projects in Illinois, Ohio, and at the M Resort in Henderson, Nev., should help stoke mid-term EBITDA growth.


 Most Read
Another Shooting Near Las Vegas Strip Casino Injures Man
 972,836 views
Vintners Oppose Napa Valley Casino
556,437 views


Conversation (0)
Be the first to comment on this article.