 Main menu


Financial
Red Rock Stock: Ron Baron, Sell-Side Analysts Maintain Bullish Outlook
Posted on: September 11, 2026, 01:50h.
Last updated on: September 14, 2026, 06:56h.


Key Points
- Famed fund manager Ron Baron expects Red Rock’s Las Vegas investments to deliver strong long-term returns
- Baron Capital maintains a longstanding stake in the Las Vegas casino operator
- Red Rock stock remains a top 10 holding in the firm’s flagship ETF


Construction disruptions at several Las Vegas properties have knocked Red Rock Resorts (NASDAQ: RRR) down 10% year-to-date, but high-profile investors are viewing the pull-back as a buying opportunity.
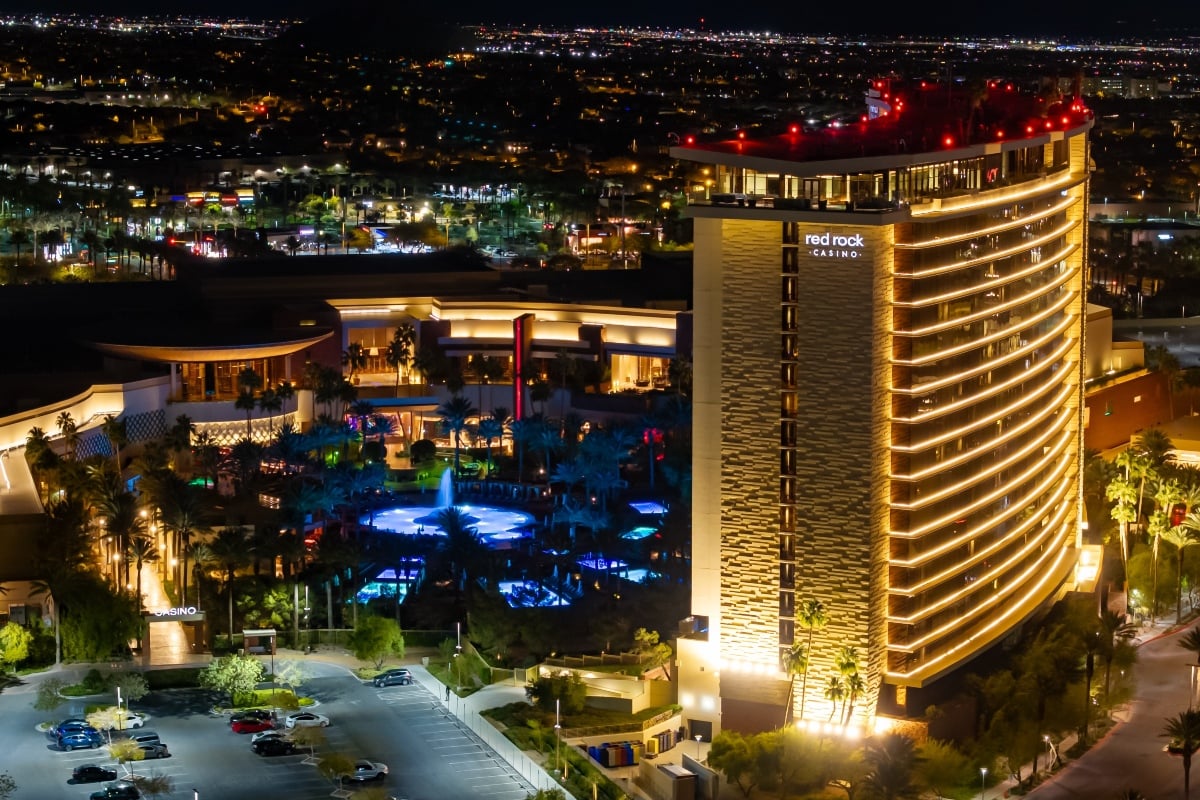
That group includes Baron Capital founder Ron Baron. In a recent investor letter for the Baron First Principles ETF (NYSE: RONB), the billionaire fund manager praised Red Rock’s strong balance sheet, noting the stock remains attractive relative to its long-term growth prospects.
“The company’s balance sheet remains strong with increased liquidity for further capital investment and shareholder returns,” wrote Baron. “We believe the stock remains attractive compared to what we believe the business can become in time.”
Red Rock stock accounts for 2.61% of the RONB portfolio, making it the ETF’s tenth-largest holding. The fund debuted last December and has $489.62 million in assets under management.
Red Rock Stock Will Make it Through Construction Disruption
This year, the “strike” against Red Rock stock is that financial results are being modestly dinged due to construction disruption at the Durango Casino & Resort in Southwest Las Vegas, Green Valley Ranch and Sunset Station.
However, the prevailing wisdom from the company, the buy-side and the sell-side is Red Rock’s enhancement efforts are examples of near-term pain, long-term gain, meaning improvements to the aforementioned Las Vegas Valley casinos will pay off over the long haul.
In the second quarter “construction disruption dissipated and investors looked ahead to the benefits of the company’s recent investments in its resorts,” added Baron.
“This should result in increased earnings and cash flow and allow the company to continue to invest in its properties while returning capital to shareholders.”
Red Rock is the only gaming stock in RONB, but another Baron ETF holds shares of Wynn Resorts (NASDAQ: WYNN).
Sell-Side Likes Red Rock Stock, Too
Due in part to its focus on the booming Las Vegas locals market, Red Rock is beloved by sell-side analysts, too. As just one example, earlier this week Texas Capital analyst David Bain initiated coverage of the stock with a “buy” rating and a $72 price target, implying potential upside of nearly 33% from current levels.
The analyst notes that with the Las Vegas area experiencing a population boom, Red Rock is garnering more of the locals segment’s wallet share due to a willingness to invest in its properties while commanding strong return on investment from those expenditures.
He also pointed to the operator’s substantial real estate holdings as a potential spark for the stock.
Red Rock historically generates “20%+ IRR on greenfield projects combines with its ~442-acre Nevada land bank, we believe offering a clear, unmatched, long-term growth pipeline,” observes Bain.
“We anticipate RRR’s next project announcement by 1H27, another relatively near-term stock catalyst, in our view,” Bain concluded.

 Most Read
Another Shooting Near Las Vegas Strip Casino Injures Man
 972,250 views
Vintners Oppose Napa Valley Casino
555,899 views


Conversation (0)
Be the first to comment on this article.