 Main menu

Asia Pacific Gaming
JPMorgan Says Concerns Over Wynn UAE Casino Are Exaggerated
Posted on: October 2, 2026, 11:35h.
Last updated on: October 5, 2026, 06:06h.


Key Points
- Investors have raised concerns over Wynn Resorts’ $5.7 billion casino development in the United Arab Emirates amid ongoing regional conflict involving Iran
- Unrest in the Middle East and softness in Macau have weighed on Wynn stock, which is down more than 36 percent year-to-date
- JPMorgan analysts say conditions in the region are moving "back to normal" faster than media reports suggest, with the UAE project remaining on track for a September 2027 opening


Investor concerns surrounding the fate of Wynn Resorts’ (NASDAQ: WYNN) Wynn Al Marjan Island project in the United Arab Emirates amid Middle East geopolitical tensions are overblown, according to JPMorgan equity research.
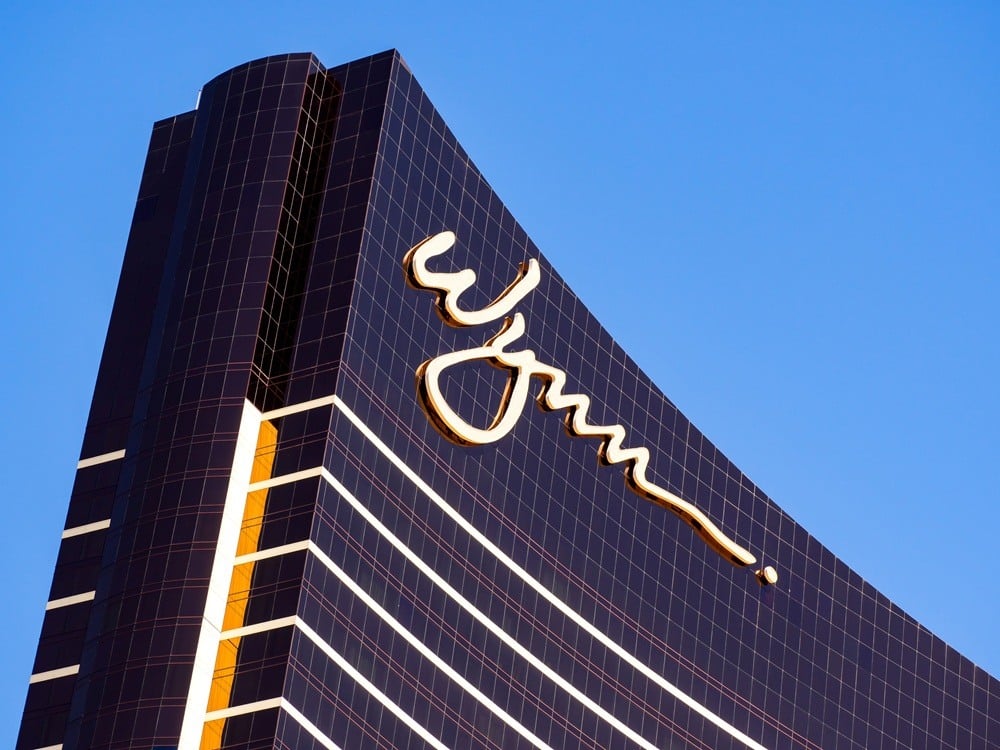
Immediately following U.S. and Israeli military strikes on Iran in late February, retaliatory strikes in the United Arab Emirates forced Wynn Resorts to briefly pause construction on its flagship project. However, the $5.7 billion Wynn Al Marjan Island development remains on track to open in September 2027.
JPMorgan analysts met with Wynn executives at the Global Gaming Expo (G2E) in Las Vegas, emerging from the meetings with a constructive outlook on the UAE project.
“Conditions in the region are a lot more ‘back to normal’ than would be indicated in the press, with lodging demand/revenue per available room in the UAE pacing -25 percent year-on-year during September, versus -50 percent [year-on-year] earlier in the year,” the analysts wrote in a report to clients.
The metrics align with recent data from the Ras Al Khaimah Tourism Development Authority, which reported that the emirate welcomed 670,000 visitors in the first half of the year despite ongoing regional conflict.
Long-Term UAE Market Prospects
Some market observers previously suggested the sell-off in Wynn shares was overdone, noting that Wall Street continues to attribute minimal value to the Middle East’s first integrated casino resort.
JPMorgan analysts noted that Wynn management “remains confident in achieving its base-to-high case steady-state assumptions,” implying the UAE could ultimately mature into one of the world’s most lucrative gaming jurisdictions.
Industry forecasts indicate the UAE could generate $3 billion to $5 billion in annual gross gaming revenue (GGR) as additional integrated resorts enter the market following Wynn Al Marjan Island’s debut.
Additionally, JPMorgan highlighted management’s belief that regional instability could extend Wynn’s exclusivity period, as UAE authorities may slow the approval timeline for competing gaming licenses.
Macau Headwinds and Cotai Expansion
Shares of Wynn Resorts are down more than 36 percent year-to-date, with analysts citing weakness in Macau—rather than the Middle East—as the primary drag on equity performance. September marked the fourth consecutive month of GGR declines in the Chinese territory, which represents Wynn’s largest operating market.
Despite current softness in Macau, JPMorgan identified upside potential from the Enclave expansion project at Wynn Palace on the Cotai Strip. The development, which features a $950 million second hotel tower, is projected to support long-term earnings before interest, taxes, depreciation, and amortization (EBITDA).
The expansion could generate approximately “$400 million of GGR and a mid/high-teens return, translating to approximately $150 million to $175 million of incremental EBITDA,” according to JPMorgan estimates.

 Most Read
Another Shooting Near Las Vegas Strip Casino Injures Man
 972,743 views
Vintners Oppose Napa Valley Casino
556,347 views


Conversation (0)
Be the first to comment on this article.